The US-China truce that suspends China’s wider rare earth export controls now runs to 10 January 2027, two months later than the 10 November date it replaced. The White House says rare earth shipments are still not back to appropriate levels, and the International Energy Agency says China did 85 per cent of the world’s rare earth refining in 2025. Outside China, Lynas Rare Earths, listed on the ASX, has signed a letter of intent with the US Department of War that includes a floor price.
What changed
On 23 September, US time, US Treasury Secretary Scott Bessent said the US-China trade truce that was scheduled to end on 10 November would be extended to 10 January. He said it in a Fox News interview reported by NBC News, after talks with China’s Vice Premier He Lifeng and as Xi Jinping arrived for a state visit. No written US readout of the extension was found, and the White House fact sheet on the state visit, dated 25 September, does not mention the new date.
Beijing’s account arrived in stages. China’s Foreign Ministry readout of the leaders’ talks on 24 September has Xi say the two trade teams reached a new joint arrangement, without giving a date. On 26 September, China’s state broadcaster, CCTV, listed eight outcomes of the 23 to 25 September visit, including that the two leaders endorsed the trade teams’ results, among them extending the Kuala Lumpur outcomes. Then, on 28 September, Beijing time, China’s commerce ministry published an explainer stating that the two sides agreed to extend the Kuala Lumpur joint arrangement to 10 January 2027 and would continue to discuss it. Bessent called it the Busan Agreement; the ministry calls it the Kuala Lumpur joint arrangement. The dates match.
Rare earths sit inside the truce through last year’s meeting in Busan, South Korea. The White House fact sheet of 1 November 2025 says China would suspend the global implementation of the expansive rare earth export controls it announced on 9 October 2025. China’s commerce ministry then suspended six October 2025 control notices in notice No. 70 of 2025, dated 7 November 2025, until 10 November 2026. Read on 27 September 2026, that notice still carried the November date.
The extension did not remove every control. In a May 2026 explainer, the commerce ministry says China applies export controls to rare earths and other critical minerals under its laws and reviews licence applications for compliant civilian uses. Its April 2025 notice on seven rare earths, notice No. 18, is not among the six notices that No. 70 suspended.
Why it binds
The extension moved a date. It did not move the refining. According to the International Energy Agency’s Global Critical Minerals Outlook 2026, the top supplier’s share of rare earth refining fell from over 90 per cent in 2023 to 85 per cent in 2025, with new projects in the United States and production increases in Malaysia. The IEA’s outlook chapter names that top refiner as China. The same release projects that the share could fall to 70 per cent by 2035 if planned projects come online as scheduled; that is a projection conditional on those projects, not a measured figure. The figure is a share of refining, also known as processing, not of mining.
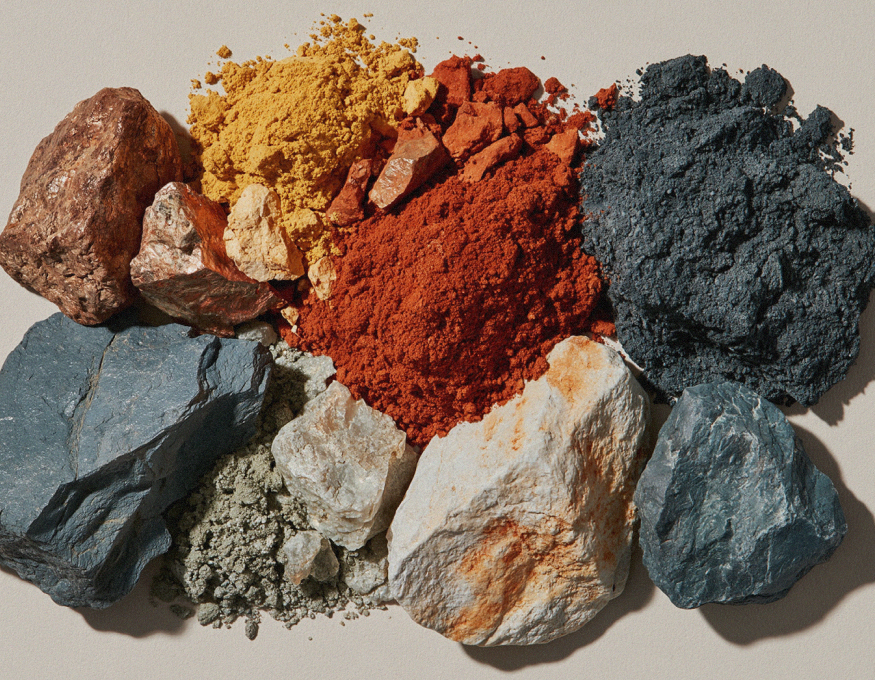
Magnets are where most people meet rare earths. The IEA refers to rare earth magnets in electric vehicles and wind turbines, and Lynas describes neodymium and praseodymium, known as NdPr, as the rare earths used in magnets.
The October 2025 rules China suspended were wider than the controls that came before them. The IEA’s executive summary says they would extend to products made outside China that contain rare earths sourced from China or are produced using Chinese technologies. The IEA estimates that about 6.5 trillion US dollars a year of downstream production outside China could be put at risk if the measures were enacted fully. That describes exposure under a condition, not a forecast.
The truce governs whether the wider October 2025 rules apply, and until when. It does not change where the refining is done.
Who absorbs it
The first party named in the record is the buyer outside China. The White House fact sheet of 25 September says the United States and China continue to work on US concerns regarding supply chain shortages related to rare earths and other critical minerals, with the goal of ensuring shipment levels return to appropriate levels. It gives no volumes and does not say shipments have stopped. Downstream manufacturing outside China carries the exposure the IEA estimates.
Supply outside China exists, and the IEA attributes the fall in China’s share to new US projects and higher output in Malaysia. Lynas Rare Earths, listed on the ASX, mines at Mount Weld in Western Australia, runs a processing facility at Kalgoorlie and separates rare earths in Malaysia, according to the company. Lynas describes itself as the only commercial producer of separated light and heavy rare earth oxides outside China. That is the company’s own description, not an independent ranking.
The US government has also stepped in as a buyer. On 16 March 2026, Lynas says, its US subsidiary signed a binding letter of intent with the US Department of War to finalise a rare earth oxide supply agreement. Under the letter, according to Lynas, about 96 million US dollars would be allocated to the purchase of light and heavy rare earth oxides over four years, to support US national security and supply chain resilience objectives, with a floor price of 110 US dollars a kilogram for NdPr oxide.
A floor price is a minimum price. Under the letter, the NdPr oxide supplied to the US is priced at no less than 110 US dollars a kilogram. It is a letter of intent to finalise an agreement, not the final agreement: Lynas’s FY26 results of 26 August 2026 still cite the March letter as its US arrangement, and its ASX announcements to 25 September contain no definitive agreement.
US defence supply chains are the third. From 1 January 2027, the procurement clause DFARS 252.225-7052 covers the entire supply chain of neodymium-iron-boron magnets, from mining through finished magnets, in covered countries, which include China. It applies to US Department of War contracts, has exceptions and does not bar commercial car makers.
What to watch
The date is 10 January 2027, when the extended truce is due to end. China’s commerce ministry says it believes a positive solution on a further extension can be found through high-level exchanges before the end of the year. That is a stated belief, not an agreed plan. If the truce lapsed without a further extension, the suspended October 2025 controls could return.
A second date comes first: the DFARS magnet restriction starts on 1 January 2027, nine days earlier.
Three documents would show whether the picture has moved. The first is a re-issued version of commerce ministry notice No. 70 carrying the January date; as of 27 September, the published notice still read 10 November 2026. The second is a White House statement that rare earth shipment levels have returned to appropriate levels, the goal its 25 September fact sheet sets. The third is a Lynas ASX announcement of a definitive supply agreement with the US Department of War, which would replace the letter of intent described above.
Read together, they form a simple rule. A re-issued notice and a statement that shipments have returned to appropriate levels before 10 January would indicate the truce is holding. An unchanged notice and no further extension as 10 January approaches would indicate the October 2025 controls could come back into force. Neither outcome changes the IEA’s 85 per cent.